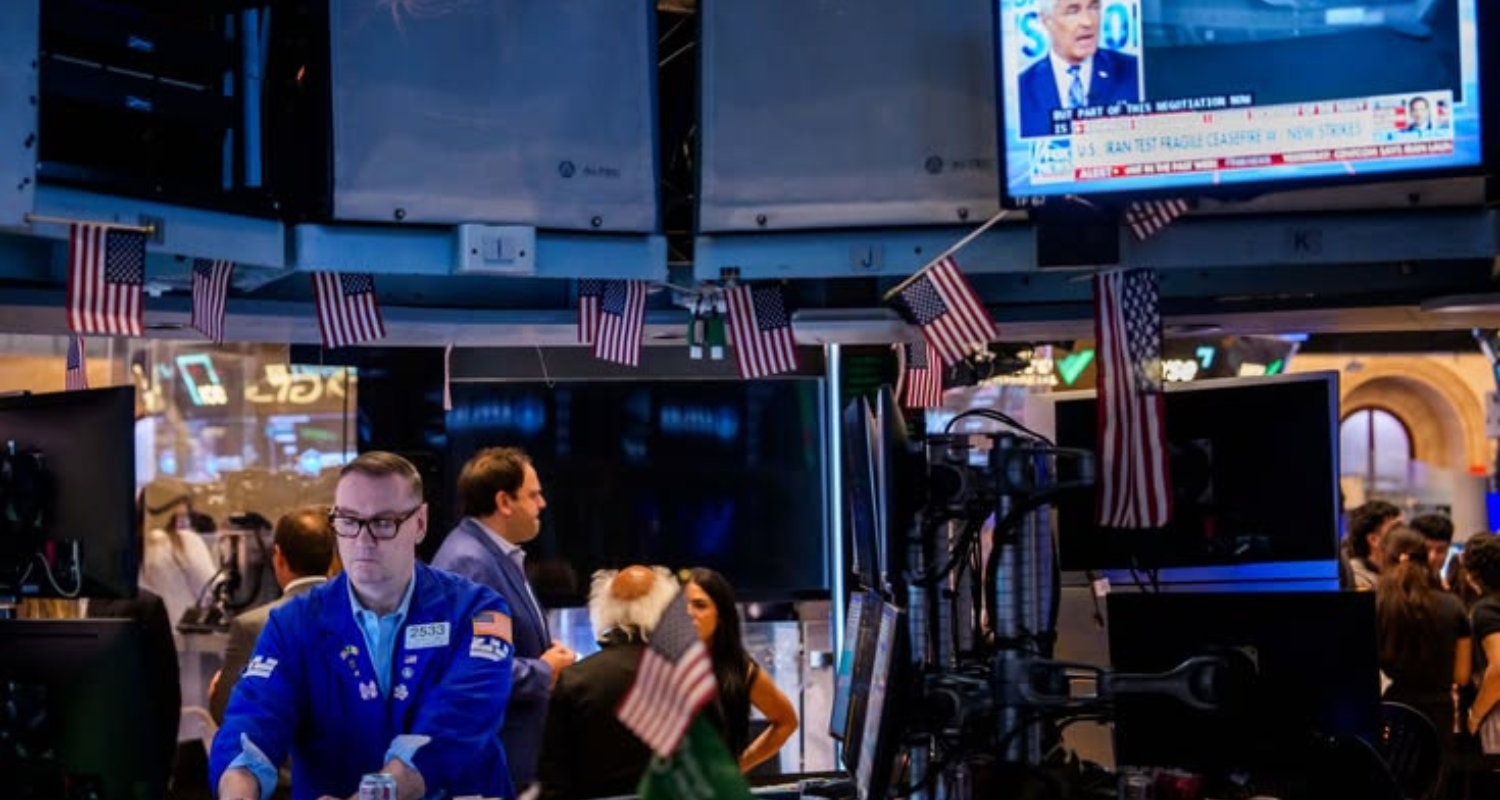
A quarterly earnings report and a household budget tell different stories about the same economy. One measures the returns generated by lending, trading and corporate dealmaking. The other tracks what remains after housing, groceries, utilities and debt payments. In October, those perspectives produced a striking contrast: four major American banks reported nearly $32 billion in quarterly profits, while Federal Reserve research showed persistent anxiety over prices and limited financial cushions for many households.
The divide is not evidence that every bank customer is falling behind, nor that every dollar earned on Wall Street comes directly from struggling families. It does, however, reveal an important disconnect: financial institutions can deliver substantial profits without producing a comparable sense of security among the people whose economic lives unfold far from the trading floor.
A Strong Quarter With Uneven Results
JPMorgan Chase, Goldman Sachs, Citigroup and Wells Fargo generated a combined $31.75 billion in third-quarter profits. JPMorgan accounted for the largest share, reporting approximately $15.31 billion. Goldman earned $5.29 billion, Citigroup brought in $5.2 billion, and Wells Fargo reported $5.95 billion. Together, their results demonstrated the earning power of institutions operating across consumer banking, investment banking and financial markets.
Yet the headline total concealed meaningful differences. Goldman’s profit rose 29% from a year earlier, while Citigroup’s increased 40%. JPMorgan, despite its substantial earnings, fell short of analysts’ expectations. Its approximately $15.3 billion profit compared with $14.4 billion a year earlier, illustrating how a bank can become more profitable and still disappoint investors who expected an even stronger performance.
That distinction matters because Wall Street evaluates success against forecasts, not simply against whether a business made money. A multibillion-dollar profit can therefore coexist with market unease. The quarter was neither an uninterrupted victory lap nor evidence of broad financial weakness. It was a demonstration of how differently large banking businesses can perform under the same economic conditions.
The Household Test Is Much Smaller
For households, financial resilience is often measured on a dramatically smaller scale. The Federal Reserve’s report on economic well-being in 2025, published in May 2026, found that 63% of adults said they would cover a hypothetical $400 emergency expense entirely with cash or its equivalent. That category includes savings and a credit card paid off at the next statement. The share was unchanged from 2024.
The remaining 37% should not automatically be described as unable to pay a $400 bill. The survey question concerns how respondents would cover the expense, not simply whether payment would be possible. Still, the findings reveal limits to readily available financial resources. Only 55% of adults reported having an emergency fund sufficient to cover three months of expenses, also unchanged from the previous year.
Prices remained a persistent source of concern. In the same survey, 91% of adults identified price increases as either a minor or major financial concern. At the same time, 73% said they were doing okay financially or living comfortably. Those figures are not contradictory. They show that maintaining day-to-day stability does not necessarily mean feeling insulated from the next increase in expenses.
Why Bank Profits Can Outpace Financial Comfort
The banks’ results reflect businesses that extend well beyond household checking accounts and credit cards. Goldman’s quarter benefited from strong equities trading, while Citigroup reported higher revenue from investment banking and wealth management. These operations respond to market activity, corporate financing needs and client investment decisions, allowing earnings to rise even when everyday affordability remains a concern.
The quarter also exposed the limits of that momentum. JPMorgan’s investment banking fees rose 14% from a year earlier but declined 8% from the second quarter. Goldman’s fees increased 21% year over year to $3.2 billion, while slipping 5.8% sequentially. The comparisons show why a strong annual growth figure does not necessarily signal that business conditions are improving from one quarter to the next.
Higher interest rates complicated the picture further. Reporting on the results described falling bond prices, weaker debt-trading revenue at JPMorgan and investment losses at Wells Fargo. Banks were not uniformly benefiting from the financial environment. Their performance depended partly on which businesses absorbed the pressure and which found opportunities within it. That complexity makes the combined profit figure informative, but incomplete.
Two Measures of Economic Strength
The household evidence also resists a simple crisis narrative. Most adults surveyed by the Federal Reserve reported at least an adequate financial position. Nevertheless, the overall stability concealed meaningful declines among some groups, including low-income, young and Black adults. A national average can hold steady while particular communities lose ground, just as aggregate bank profits can rise while individual institutions encounter setbacks.
Ultimately, the nearly $32 billion earnings total measures the profitability of four major banks during one quarter. It does not measure how comfortably Americans can meet their obligations. Read alongside the Federal Reserve’s household findings, it offers a more revealing portrait: an economy capable of generating enormous institutional earnings while leaving financial security unevenly distributed. The central question is not whether Wall Street succeeded, but how much that success says about life beyond it.